Buying a home in Greater Boston isn't exactly inexpensive. Whether you're looking in Norwood, Newton, Needham, Dedham, or the surrounding communities, today's mortgage rates can make even a reasonably priced home feel out of reach.
But what if the solution isn't necessarily finding a cheaper home?
What if it's exploring a different way to finance the one you want?
That's exactly what more homebuyers are doing, and it's bringing an often-overlooked mortgage option back into the conversation.
Why Adjustable-Rate Mortgages Are Making a Comeback
According to the Mortgage Bankers Association, adjustable-rate mortgages (ARMs) represented approximately 10.5% of mortgage applications in mid-October 2026.
The reason? Lower introductory interest rates.
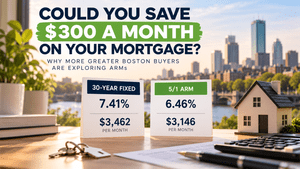
During the week ending October 16, the MBA reported these average contract rates:
30-year fixed mortgage: 7.41%
5/1 adjustable-rate mortgage: 6.46%
That's nearly a full percentage point difference.
And in a market like Greater Boston, where buyers may be borrowing $400,000, $500,000, or considerably more, that difference can translate into meaningful monthly savings.
What Could That Actually Save You?
Let's look at an example using a $500,000 mortgage with a 30-year amortization schedule.
Mortgage optionMonthly principal & interest30-year fixed at 7.41%Approximately $3,4625/1 ARM at 6.46%Approximately $3,146Initial monthly savingsApproximately $316
That's roughly $3,800 in the first year in payment savings, assuming those rates remain applicable during that period.
Over five years, the payment difference could total approximately $19,000.
Those are meaningful numbers for a household managing childcare, property taxes, insurance, and the other costs of homeownership.
However, lower payments don't automatically mean an ARM is the better long-term financial decision.
How Does an Adjustable-Rate Mortgage Work?
An adjustable-rate mortgage starts with an interest rate that's fixed for a specific number of years.
For example, a 5/1 ARM has a fixed interest rate for the first five years. After that, the rate can adjust annually based on the loan's terms and a market index.
Other options include 7-year and 10-year introductory fixed periods, depending on the lender.
The advantage is potentially paying less interest during those early years.
The trade-off is uncertainty about what happens after the introductory period expires.
Your interest rate could increase, decrease, or remain relatively similar.
Who Might Benefit From an ARM in Massachusetts?
An ARM may be worth exploring if:
You're purchasing a starter home and expect to move within several years.
You're relocating to Greater Boston and aren't certain how long you'll remain in the property.
You expect your income to increase and have the financial flexibility to manage future payment changes.
You want to compare multiple financing strategies before committing to a purchase.
For example, someone purchasing a first home in Norwood who expects to move into a larger home within five to seven years may have different financing priorities than a family purchasing its long-term home in Needham.
Neither situation automatically makes an ARM the right choice, but they deserve different conversations.
What Are the Risks?
Here's the part buyers shouldn't overlook.
When the introductory fixed period ends, your interest rate and monthly payment may increase.
Although ARMs generally have limits on how much rates can change, those increases can still affect your household budget.
Before choosing an ARM, ask your lender:
What's the maximum payment I could face after the initial fixed period?
How frequently can the rate adjust?
What are the initial, periodic, and lifetime interest-rate caps?
How do closing costs and loan fees compare with a fixed-rate mortgage?
Can I comfortably afford this mortgage if refinancing isn't available?
Never assume you'll be able to refinance before the rate adjusts. Refinancing depends on future rates, your financial qualifications, home equity, and lending conditions.
Are Today's ARMs Like the Mortgages That Contributed to the 2008 Housing Crisis?
Not exactly.
Today's mortgage market operates under stronger underwriting and ability-to-repay requirements than those associated with many of the risky loan products offered before the financial crisis.
Lenders generally must verify income and evaluate borrowers' ability to repay qualifying mortgages.
However, that doesn't eliminate the risk of future payment increases.
The important distinction is understanding what you're borrowing, how the rate can change, and whether the mortgage fits your long-term financial plans.
The Bottom Line for Greater Boston Homebuyers
When you're buying a home in Massachusetts, the purchase price is only part of the equation.
Your mortgage structure can significantly influence your monthly payment and overall financial flexibility.
For some buyers, a traditional fixed-rate mortgage will remain the strongest option.
For others, an adjustable-rate mortgage deserves a closer look.
The goal isn't simply to find the lowest payment today. It's to choose financing that works for your future.
If you're considering buying a home in Norwood, Newton, Needham, or anywhere throughout Greater Boston, I can help you evaluate available properties and connect you with a qualified mortgage professional to compare financing options.
Mike Panza, Realtor®
Panza Home Group | Real Broker MA, LLC
Mortgage examples are illustrative and exclude taxes, homeowners insurance, mortgage insurance, and other expenses. Rates, APRs, points, fees, and qualification requirements vary. Consult a licensed mortgage loan originator for personalized financing advice.